After the decree
Buying again, on one income
You can buy after a divorce, and many people buy within a year. The questions are what the lender will count, what the old joint mortgage does to your ratios, and what help exists for a single-income buyer in Colorado. Then it is just a home search.
Next free Zoom: second Saturday, 9:00 AM Mountain · in a few days · Divorce and the House: sell it, keep it or buy out?
Call or text 303-955-4220. A live person answers. Not a robot, not a phone tree.
After the decree is entered
Most lenders will not close a purchase during a pending divorce. A signed, court-entered decree is the document.
Support counts with a history
Six months of receipt (three for FHA on court-ordered support) and three years of continuance.
Assigned to your ex? It may not count
A mortgage assigned to your ex in the decree can be excluded from your debt ratio with the decree in the file.
You may be a first-time buyer again
No ownership in three years qualifies for CHFA FirstStep; metroDPA has no first-time rule at all.
You can apply the day the decree is entered. Lenders will count your wages plus maintenance and child support you have received for six months (three for FHA, court-ordered) and will keep receiving for three years. The joint mortgage on the old house counts against you unless the decree assigns it to your ex, or your ex has paid it for 12 documented months. Colorado has real down-payment help for single-income buyers, and the full MLS search is on kennarealestate.com, where nobody has to know why you are looking.
What lenders need from you
- The entered decree or a court-approved separation agreement, not a draft. It is how they verify support and exclude assigned debts.
- Proof of support received: bank statements or the state disbursement record for six months (conventional) or three months (FHA, court-ordered). Lump-sum equalization payments are not income.
- Continuance: the support must run at least three years past closing. A child who turns 19 in two years, or maintenance that ends in 30 months, cannot be counted for that portion.
- The old mortgage: excluded from your ratios if the decree assigns it to your ex (Fannie Mae B3-6-05: “the lender is not required to count this contingent liability”), or if your ex is on the note and 12 months of statements show them paying with no lates.
- Credit with no recent lates. One 30-day late on the joint mortgage in the last 12 months is the most common reason a post-divorce purchase fails. Protect it during the case.
Down-payment help in Colorado for one-income buyers
Rent for a year or buy now?
Honest answer: rent if your income is changing, your support is not yet flowing, your credit has a fresh late, or you do not know which side of town your life will be on in a year. Buy if the decree is entered, the numbers work at 43 percent of your gross income or less with room for repairs, and you plan to stay at least three years. The worst outcome is buying a second house you have to sell in 18 months. At today’s rates every $100,000 borrowed costs about $660 a month in principal and interest; work backward from the payment you can carry alone.
Where to search
Every home for sale in Colorado, straight from the MLS, is on kennarealestate.com. Search by city, ZIP, neighborhood or address, save searches, and get alerts. If downsizing is the plan, the complete list of 55+ communities in Colorado is there too. Nothing on our sites asks why you are looking.
Buying again after divorce: 14 questions, answered for Colorado
Every answer below is its own page, written for a Colorado reader who is buying on one income and starting over. Read the one that matches your week.
The benefits of owning your own home after divorce
Owning your own home after divorce builds equity, gives you control of the space and fixes your payment. On a $450,000 Colorado home that is about…
Read the answerBuy before or after the marital home sells in Colorado
Whether you buy before or after the marital home sells in Colorado depends on your decree's sale date, your two-loan qualifying and your cash for…
Read the answerBuying a home after divorce near the kids' other parent
Buying a home after divorce with shared parenting time comes down to one number in Colorado: drive minutes between the two homes. Stay 10 to 20…
Read the answerBuying a home alone after a divorce at 50 or older in Colorado
Buying a home alone after 50 works in Colorado when you pick one-level living you can maintain by yourself and qualify with documented retirement…
Read the answerBuying a home with a new partner after divorce in Colorado
Buying a home with a new partner after divorce protects you when you hold title as tenants in common and sign a written co-ownership agreement that…
Read the answerCan I use my divorce settlement as a down payment in Colorado?
Yes, you can use a divorce settlement as a down payment in Colorado when the money has a paper trail. This post shows what lenders verify, how QDRO…
Read the answerHouse hacking after divorce in Colorado: duplex, roommate or ADU
House hacking after divorce means you live in one unit or room and rent the rest, which cuts a $4,514 duplex payment to about $2,114 a month in this…
Read the answerHow soon after divorce can I buy a house in Colorado?
You can buy a house after divorce in Colorado as soon as the decree is signed, because the state sets no waiting period. Your lender sets the dates…
Read the answerHow to choose your first home after divorce: a new chapter checklist
Choose your first home after divorce in Colorado by writing what you need, want and refuse before you tour, then scoring every home against the same…
Read the answerCan I get a mortgage with alimony and child support in Colorado?
You can get a mortgage with alimony and child support in Colorado when the decree orders the payments, you have 6 months of history and the payments…
Read the answerHow to rebuild credit after divorce before buying in Colorado
You can rebuild credit after divorce in about 90 days when you fix joint accounts, pay balances under 30 percent of each limit and stop new…
Read the answerBuying a new home after divorce while still on the old mortgage
You can buy a home in Colorado while you are still on the old mortgage after divorce. The lender drops the old payment from your ratio when the…
Read the answerVA loan after divorce in Colorado: what happens to your entitlement
A VA loan after divorce works in Colorado, but your entitlement stays tied to the marital home until that loan is paid off, refinanced or assumed by…
Read the answerWhat one income buys in the Denver metro after divorce in 2026
What one income buys in the Denver metro after divorce runs from about $259,000 on $70,000 a year to about $595,000 on $150,000, at an example 6.5…
Read the answerQuestions people ask on this page
How soon after divorce can I get a mortgage?
As soon as the decree is entered and you can document income and the old loan’s treatment. There is no waiting period in the rules; the six-month support history and any recent lates are what set the real timeline.
Can I buy while the divorce is pending?
Rarely. The automatic injunction and the lender’s need for a final allocation of debts and support usually make it wait. Ask your attorney; some agreed cases get a court order that lets it happen.
Does alimony count as income for a mortgage?
Yes, with the decree, six months of receipt (three for FHA on court-ordered support) and three years of continuance. Child support is non-taxable and can often be grossed up by about 25 percent.
I have never been on a mortgage. Do I have credit?
Maybe thin. Open one card in your own name now, keep the balance under 30 percent of the limit, and pay it monthly. Six months of that helps more than people expect.
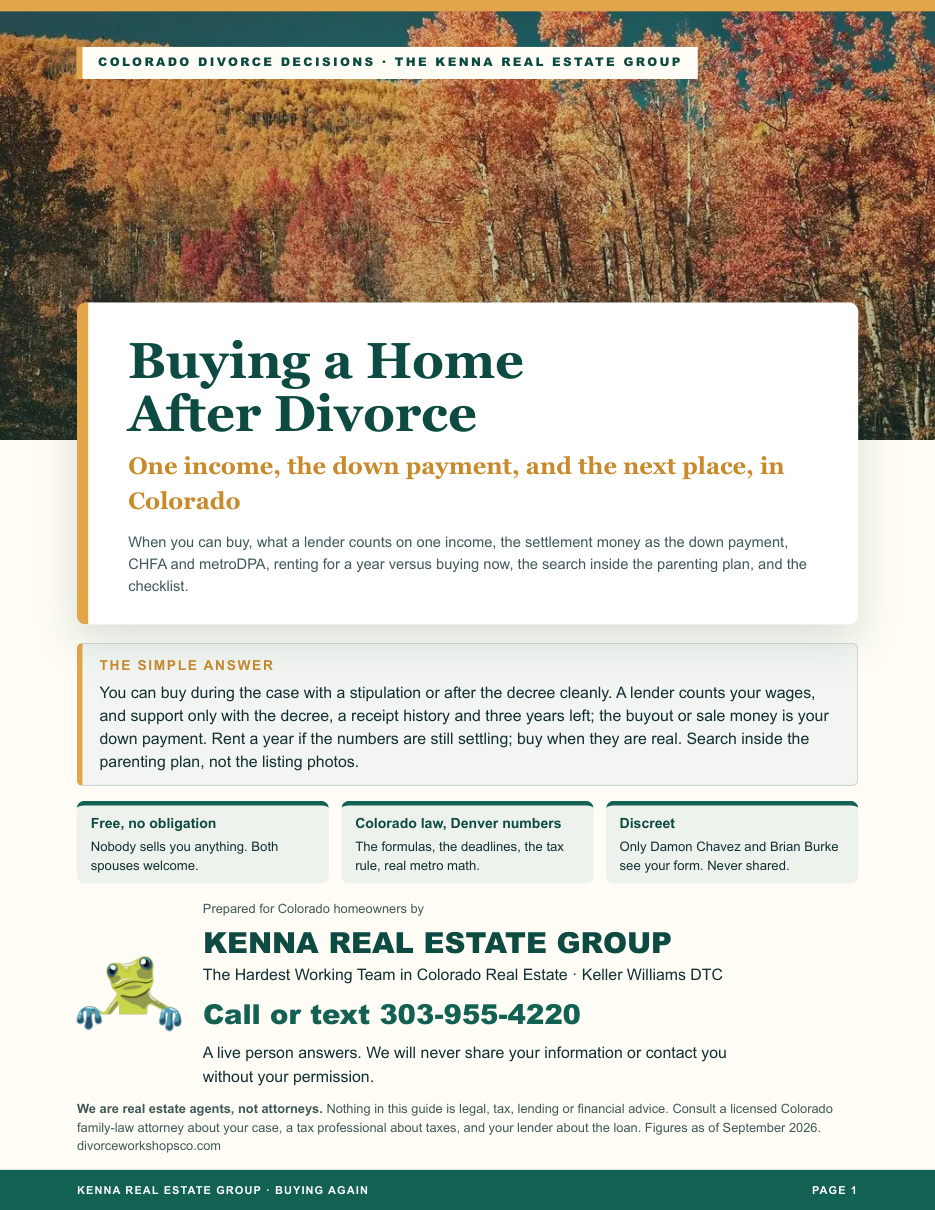
Buying a Home After Divorce in Colorado: One Income, the Down Payment, the Next Place
The short guide written for this page. Free, 4 pages, plain English, Colorado numbers. Fill in your name, email and phone and the PDF opens right away. Only Brian Burke and Damon Chavez see the form.
Where to go next
- The house: keep, sell or buy out
- Who gets the house in Colorado
- Keep the house
- Sell the house
- What is the house worth
- The mortgage after divorce
- Taxes when you sell
- Buying after divorce
- Why a divorce realtor
- Mike Oswald at Rate: refinance and buyout math
- Selling in a divorce: FAQ on kennarealestate.com
- Search every home for sale in Colorado
Search for the next place
Full Colorado MLS search on kennarealestate.com. No account needed to look.
Call your Colorado divorce agent
Questions about the house, the deed or the decree?
Call us today to talk through your situation and how we can help. A live person answers. Not a robot, not a phone tree.
Free and confidential
Ask us about the house
Tell us where you are in the process and what you are trying to figure out. We will answer honestly, including when the honest answer is to wait. Free and confidential. You do not need to be ready to sell, and there is no pressure to list your home. Or bring your question to the free monthly Zoom, Divorce and the House, second Saturday at 9:00 AM.
303-955-4220A live person answers. Not a robot, not a phone tree. Prefer email? homes@kennarealestate.com
Divorce Decisions™: Colorado divorce workshops and education. Real estate services provided by The Kenna Real Estate Group at Keller Williams DTC. Not legal, tax, lending or financial advice.
Ready to sell or buy? Kenna Real Estate Group handles the house.
- Divorce for women: the house, the money, the next move (kennarealestate.com)
- Real estate and divorce in Colorado: divorce realtors in every Front Range city and county
- Divorce and real estate articles on kennarealestate.com
Call or text 303-955-4220. A live person answers.